Software Market Trends, September 2026: Valuations Recover, Earnings Season Delivers a De-Rating
Dedale's September 2026 software market update covers valuation recovery, a GovTech M&A deep dive, record AI investment, and a Q2 2026 earnings season that delivered broad beats but a market de-rating.
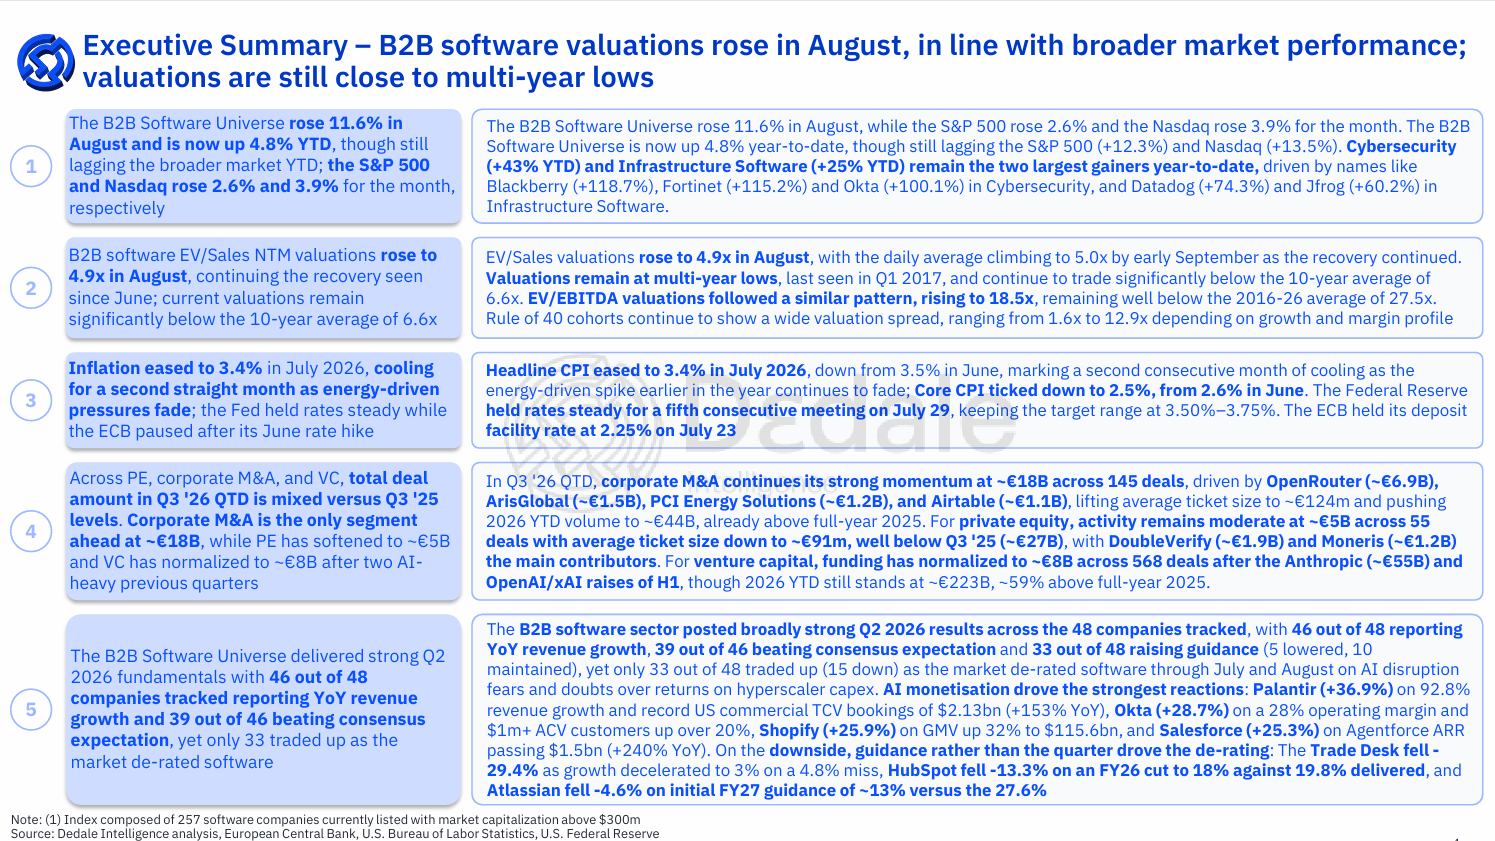
August delivered a run of contradictions for B2B software investors. Valuations climbed, inflation kept cooling, and dealmakers pushed deal volumes to new highs, yet a strong earnings season still triggered a broad de-rating across the sector. The B2B Software Universe rose 11.6% in August, now up 4.8% year-to-date, while the S&P 500 and Nasdaq rose 2.6% and 3.9% for the month, respectively.
This update from Dedale Intelligence covers the key themes that shaped B2B software and technology markets in August. For context on where things stood one month prior, see Dedale Intelligence's July 2026 Market Trends article.
Valuations: the recovery continues, but discipline remains
The B2B Software Universe's 4.8% year-to-date performance still lags the S&P 500 (+12.3%) and the Nasdaq (+13.5%). Cybersecurity (+43% YTD) and Infrastructure Software (+25% YTD) remain the strongest-performing segments, led by Blackberry (+118.7%), Fortinet (+115.2%), and Okta (+100.1%) in cybersecurity, and Datadog (+74.3%) and Jfrog (+60.2%) in infrastructure software.
EV/Sales NTM valuations rose to 4.9x in August, with the daily average climbing to 5.0x by early September. That recovery still leaves valuations at multi-year lows last seen in Q1 2017, well below the 10-year average of 6.6x. EV/EBITDA multiples followed the same pattern, rising to 18.5x against a 2016 to 2026 average of 27.5x.
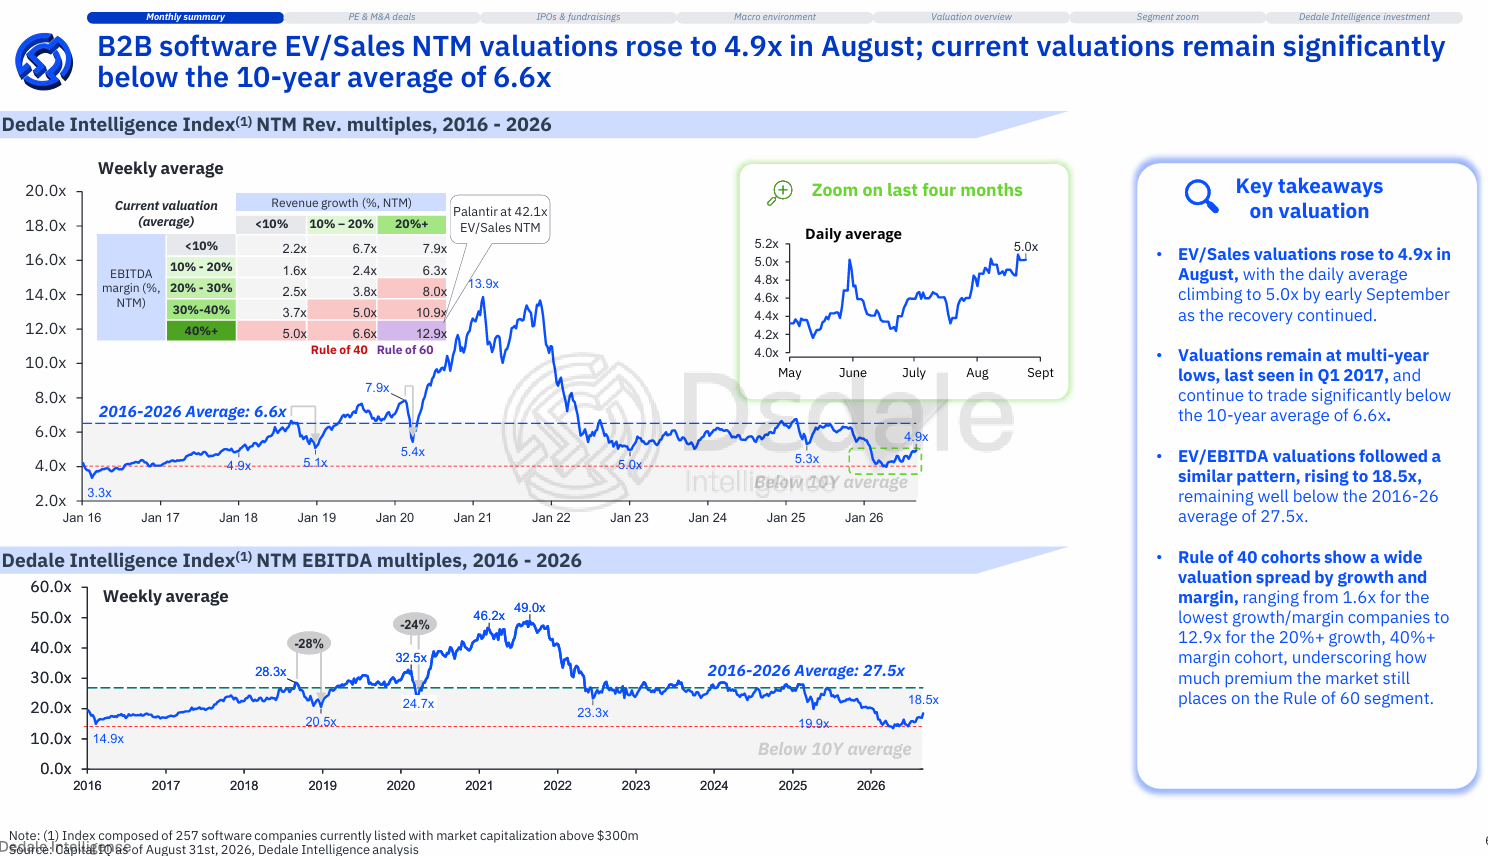
Dispersion remains wide: Rule of 40 cohorts trade from 1.6x EV/Sales for sub-10% growth, sub-10% margin companies up to 12.9x for the rare 20%+ growth, 40%+ margin cohort, and high-growth companies (20%+ revenue growth) command 9.1x versus 4.6x for mid-growth peers. Geography still matters too: the US-Europe valuation premium held at 94% in August, with North American companies at 5.7x versus 3.0x for European peers, a gap Dedale Intelligence attributes to growth stage, cash generation, and SaaS delivery mix.
Macro: inflation keeps cooling, central banks diverge
Headline CPI eased to 3.4% in July 2026, down from 3.5% in June, a second consecutive month of cooling as the energy-driven spike earlier in the year fades. Core CPI ticked down to 2.5%, from 2.6% in June. The Federal Reserve held rates steady for a fifth consecutive meeting on July 29, keeping its target range at 3.50% to 3.75%.
The European Central Bank held its deposit facility rate at 2.25% on July 23, pausing after a surprise 25 basis point hike in June, its first tightening move since 2023. Markets are pricing another 25 basis point move to 2.50% at the ECB's September 10 meeting, which would keep it the only major central bank still actively tightening.
Download the full September 2026 Market Intelligence report
GovTech: corporates consolidate while AI adoption stays cautious
This month's segment deep-dive covers GovTech, a market still shaped more by incumbents than by challengers. Corporate acquirers account for 40 of the 73 GovTech deals tracked year-to-date 2026 (around 55%), leading deal count in 6 of the first 8 months of the year. Product expansion drives 22 of those 40 corporate deals (around 55%), as vendors like Berger-Levrault, Groupe JVS, and NEC add adjacent modules to cross-sell into their existing local-authority customer base. Geographic expansion is a smaller but consistent driver, at 6 of 40 deals (around 15%).
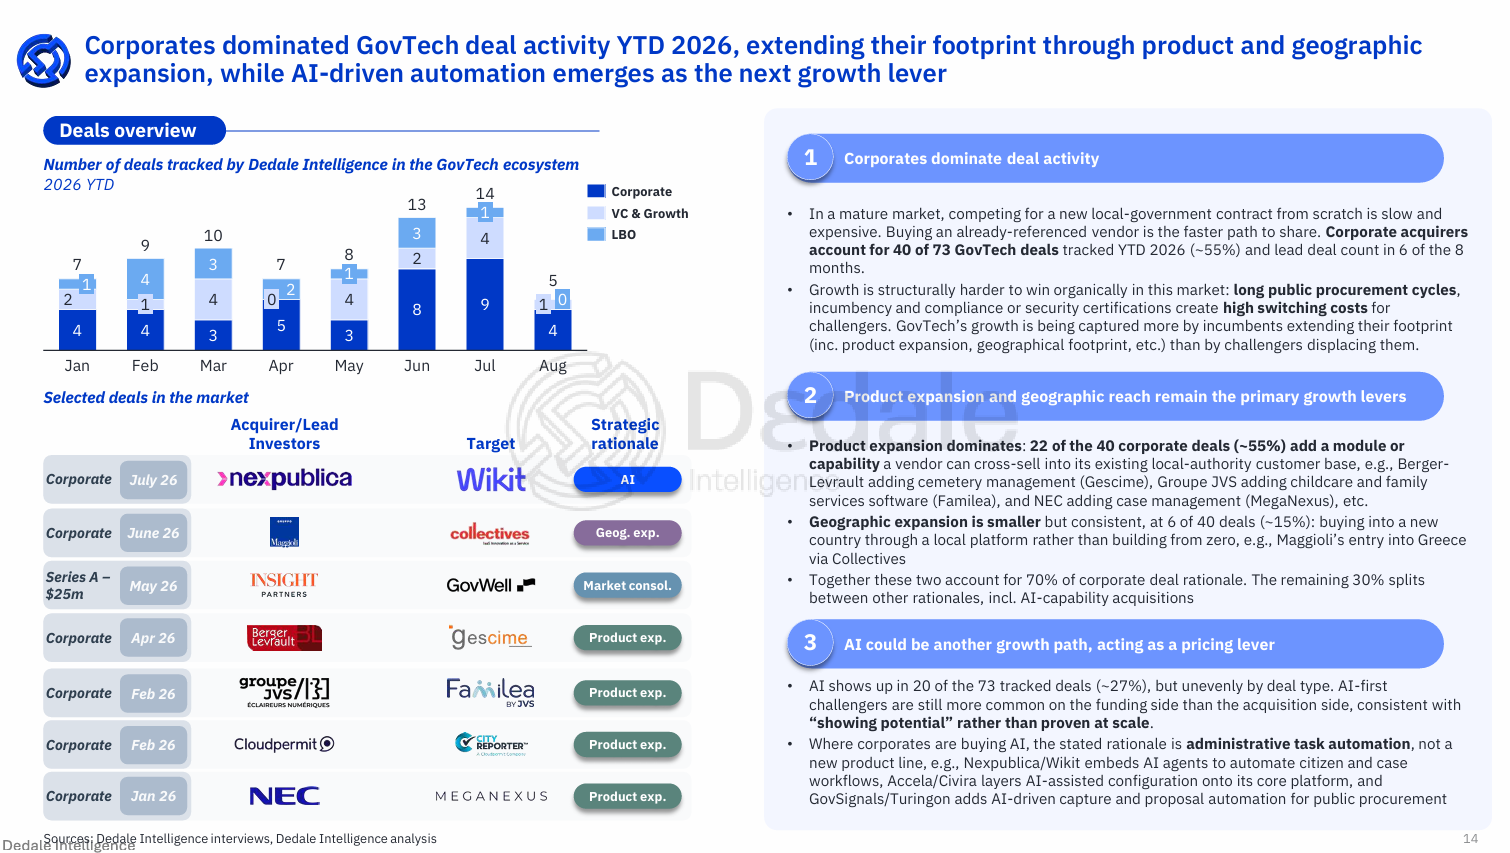
AI shows up in 20 of the 73 tracked deals (around 27%), more common on the funding side than the acquisition side, consistent with AI-first challengers in GovTech still showing potential rather than proving themselves at scale. Where corporates are buying AI, the rationale tends to be administrative task automation rather than a new product line, as seen in Nexpublica's acquisition of Wikit.
Dedale Intelligence's own survey of local authorities across the US, UK, and France, part of our ongoing GovTech software coverage, found security and compliance to be the top-ranked criterion for core ERP purchasing in the US (4.7 out of 5) and UK (4.5), tying with functional depth in France (4.2). AI and product innovation ranks last or near-last in every market, with staff skills, budget constraints, and data residency consistently cited as the top barriers to AI adoption.
Deal activity: M&A hits new highs, AI investment tops $361B year-to-date
Across private equity, corporate M&A, and venture capital, Q3 2026 quarter-to-date activity is mixed but directionally strong. Corporate M&A continues its momentum, with roughly €18 billion invested across 145 deals, driven by OpenRouter (around €6.9 billion), ArisGlobal (around €1.5 billion), PCI Energy Solutions (around €1.2 billion), and Airtable (around €1.1 billion), pushing 2026 year-to-date volume to around €44 billion, already above full-year 2025.
Private equity activity remains more moderate, at roughly €5 billion across 55 deals, well below Q3 2025's €27 billion. Venture capital funding normalized to around €8 billion across 568 deals after two AI-heavy previous quarters, though 2026 year-to-date VC volume still stands at around €223 billion, about 59% above full-year 2025. Headline transactions in July and August included Moneris Solutions (Francisco Partners, approximately CAD 2 billion), DoubleVerify (The Nielsen Company, $2.15 billion), OpenRouter (Stripe, approximately $8 billion), and Airtable (Bending Spoons, $1.285 billion).
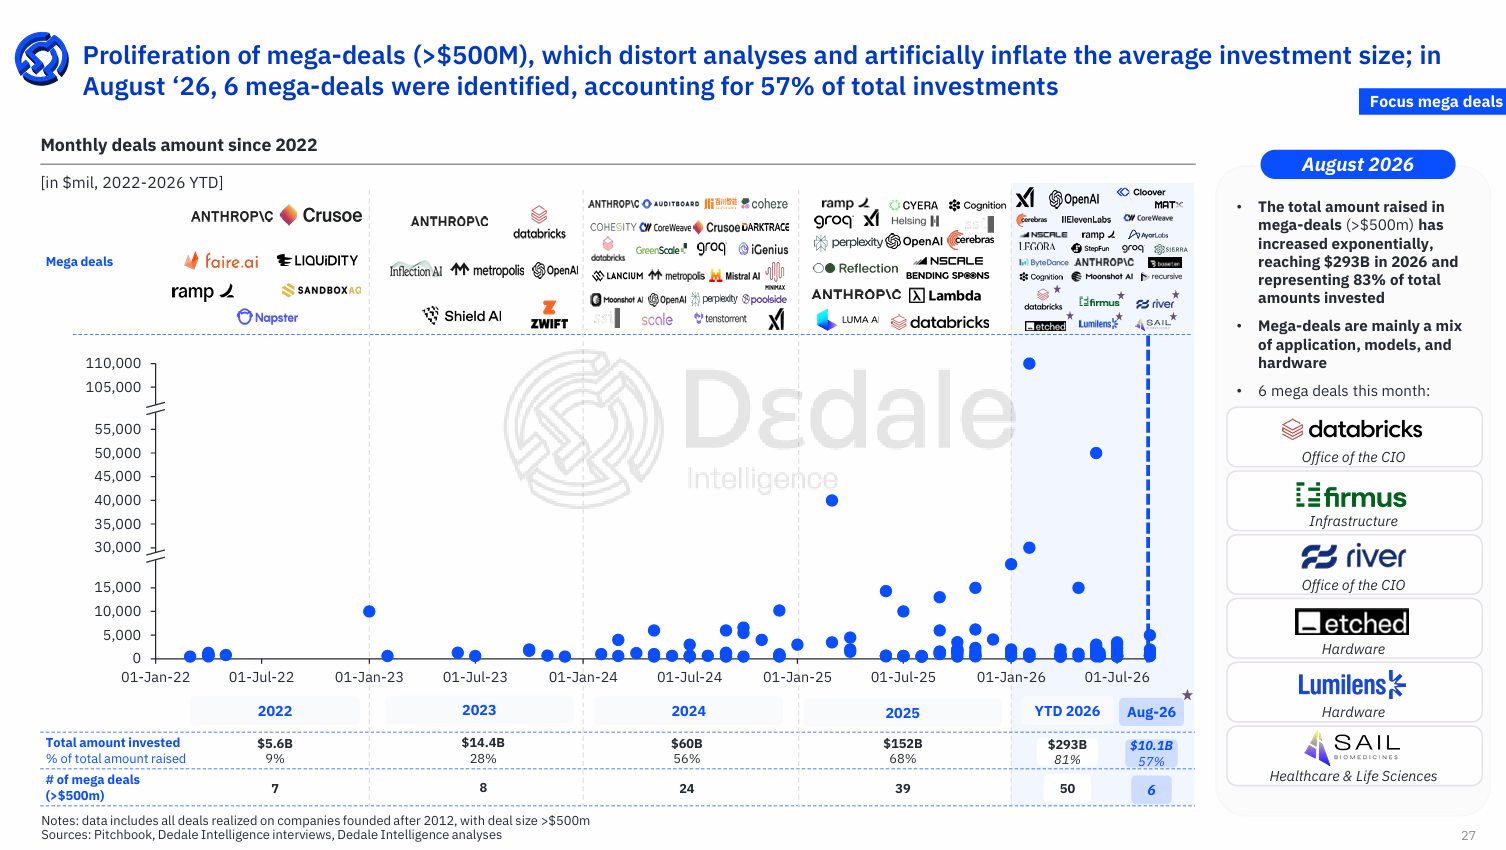
AI investment continues to define the venture landscape. Total AI value chain investment in 2026 year-to-date has already surpassed the full 2025 total, reaching $361 billion as of August, with $17.7 billion invested across 119 AI-related deals in August alone. Six mega-deals (over $500 million), including Databricks, Firmus, River, Etched, Lumilens, and SAIL, accounted for 57% of the month's total investment. Excluding mega-deals, the underlying trend for sub-$500 million deals remains upward, with 2026 year-to-date volume at around $68 billion, still above the pace of 2025.
IPOs: the window stays shut for B2B software
July saw 32 IPOs and August saw 23, in line with or below long-term averages, but neither month produced a significant B2B software listing, with more activity happening on the take-private and M&A side instead. Among B2B software companies that have gone public over the past year, Navan, Netskope, Via, Figma, NIQ, and mntn all posted positive three-month stock performance, while CoreWeave pulled back 11.0% despite still trading 123.4% above its IPO price, and HawkEye360 is down 48.9% since its May IPO.
Q2 2026 earnings: broad beats, selective rewards
The earnings season running through July and August told its own story about where investor conviction now sits. Across the 48 B2B software companies Dedale Intelligence tracks, 46 reported year-over-year revenue growth, 39 beat consensus expectations, and 33 raised guidance (against 5 that lowered and 10 that maintained). Yet only 33 traded up, as the broader market continued to de-rate software through July and August on AI disruption fears and doubts over returns on hyperscaler capital expenditure.
Selected highlights from the cohort:
- Palantir rose 36.9% on 92.8% revenue growth and record US commercial bookings of $2.132 billion (+153% year-over-year).
- Okta gained 28.7% on a 28% operating margin and over 20% growth in $1 million-plus annual contract value customers.
- Shopify rose 25.9% on gross merchandise volume up 32% to $115.6 billion.
- Salesforce rose 25.3% as Agentforce annual recurring revenue passed $1.5 billion (+240% year-over-year).
- The Trade Desk fell 29.4% as growth decelerated to 3% on a 4.8% miss.
- HubSpot fell 13.3% on a FY26 guidance cut to 18% against 19.8% delivered.
- Atlassian fell 4.6% on initial FY27 guidance of around 13% versus the 27.6% just delivered.
How Dedale Intelligence tracks B2B software markets
Dedale Intelligence publishes a monthly B2B software Market Session for private equity funds, corporate development teams, and M&A advisors across North America and Europe. The analysis in this article is drawn from the September 2026 Market Session. The full report contains detailed valuation tables by segment and cohort, the complete GovTech segment deep-dive, the full IPO tracker, earnings coverage across all 48 companies, and the segment zoom covering the full B2B software universe. For related analysis, see Dedale Intelligence's take on cybersecurity software and the Office of the CIO and CTO.
Download the full September 2026 Market Intelligence report
To discuss any of the themes in this update or go deeper on a specific segment, deal, or valuation trend, contact the Dedale Intelligence team

Explore our resources
How Sagard works on supply chain software with Dedale
AI, Grid Inspection & the AI-Ready Utility with Vikhyat Chaudhry (Buzz Solutions)
Frequently asked questions
September 2026 Software Market Trends: Common Questions
Answers to the most common questions about Dedale's September 2026 software market update.
Did B2B software valuations recover in August 2026?
Yes. The B2B Software Universe rose 11.6% in August 2026, and EV/Sales NTM multiples rose to 4.9x (5.0x on a daily average basis by early September). Valuations remain well below the 10-year average of 6.6x and are still at levels last seen in Q1 2017.
Which B2B software segments performed best in August 2026?
Cybersecurity (+43% year-to-date) and Infrastructure Software (+25% year-to-date) remain the two strongest-performing segments in 2026, driven by companies including Blackberry, Fortinet, Okta, Datadog, and Jfrog.
What is happening with inflation and interest rates?
Headline CPI eased to 3.4% in July 2026, a second consecutive month of cooling, while core CPI ticked down to 2.5%. The Federal Reserve held rates steady for a fifth consecutive meeting, and the European Central Bank held its deposit rate at 2.25% after a surprise hike in June, with markets pricing another move in September.
Why is there so much M&A activity in GovTech?
Corporate acquirers, rather than new entrants, are driving GovTech consolidation: they accounted for 40 of 73 tracked deals year-to-date 2026, mostly to add product modules or expand geographically into an existing local-authority customer base.
Why did so many companies beat earnings but still see their stock fall?
Of the 48 B2B software companies Dedale Intelligence tracks, 39 beat consensus, yet only 33 traded up. The market is increasingly pricing guidance and AI-related growth durability over the quarter just delivered, which is why misses on forward guidance, such as HubSpot's and Atlassian's, triggered sharp de-ratings despite otherwise solid results.
Newsletter
Fresh insights, straight to your inbox
Trusted by 2,000+ clients
Get started
Investor, operator, or industry expert, there's a path for you.