Market trends October 2025
Dedale's software market update for October 2025: valuations, stock performance, deals & investor insights
Market Performance
September marked a modest gain for B2B software stocks. Our index of 250+ public companies rose +0.7%, trailing the broader indices:
- B2B Software Index: +0.7%
- S&P 500: +3.2%
- Nasdaq: +5.0%
Despite muted recent performance, this follows strong gains in 2024.
By segment, majors (Oracle, Microsoft,etc.) continue to lead the pack, up nearly +30% YTD, while infrastructure and industrial software also posted healthy gains thanks to the AI wave and industrial digitization. On the downside, supply chain management software remains under pressure amid trade and tariff headwinds, while workflow, CRM, and HCM vendors face valuation strain due to anticipated AI disruption.
U.S. inflation rose from 2.7% in July to 2.9% in August; in September, the Federal Reserve cut rates by 25 basis points, marking its first rate cut of the year amid rising concerns over labor market weakness and slowing job growth. In Europe, the ECB kept its deposit rate unchanged at 2.0%, citing weak growth, persistent inflation, and an exceptionally uncertain outlook.
Market Valuations
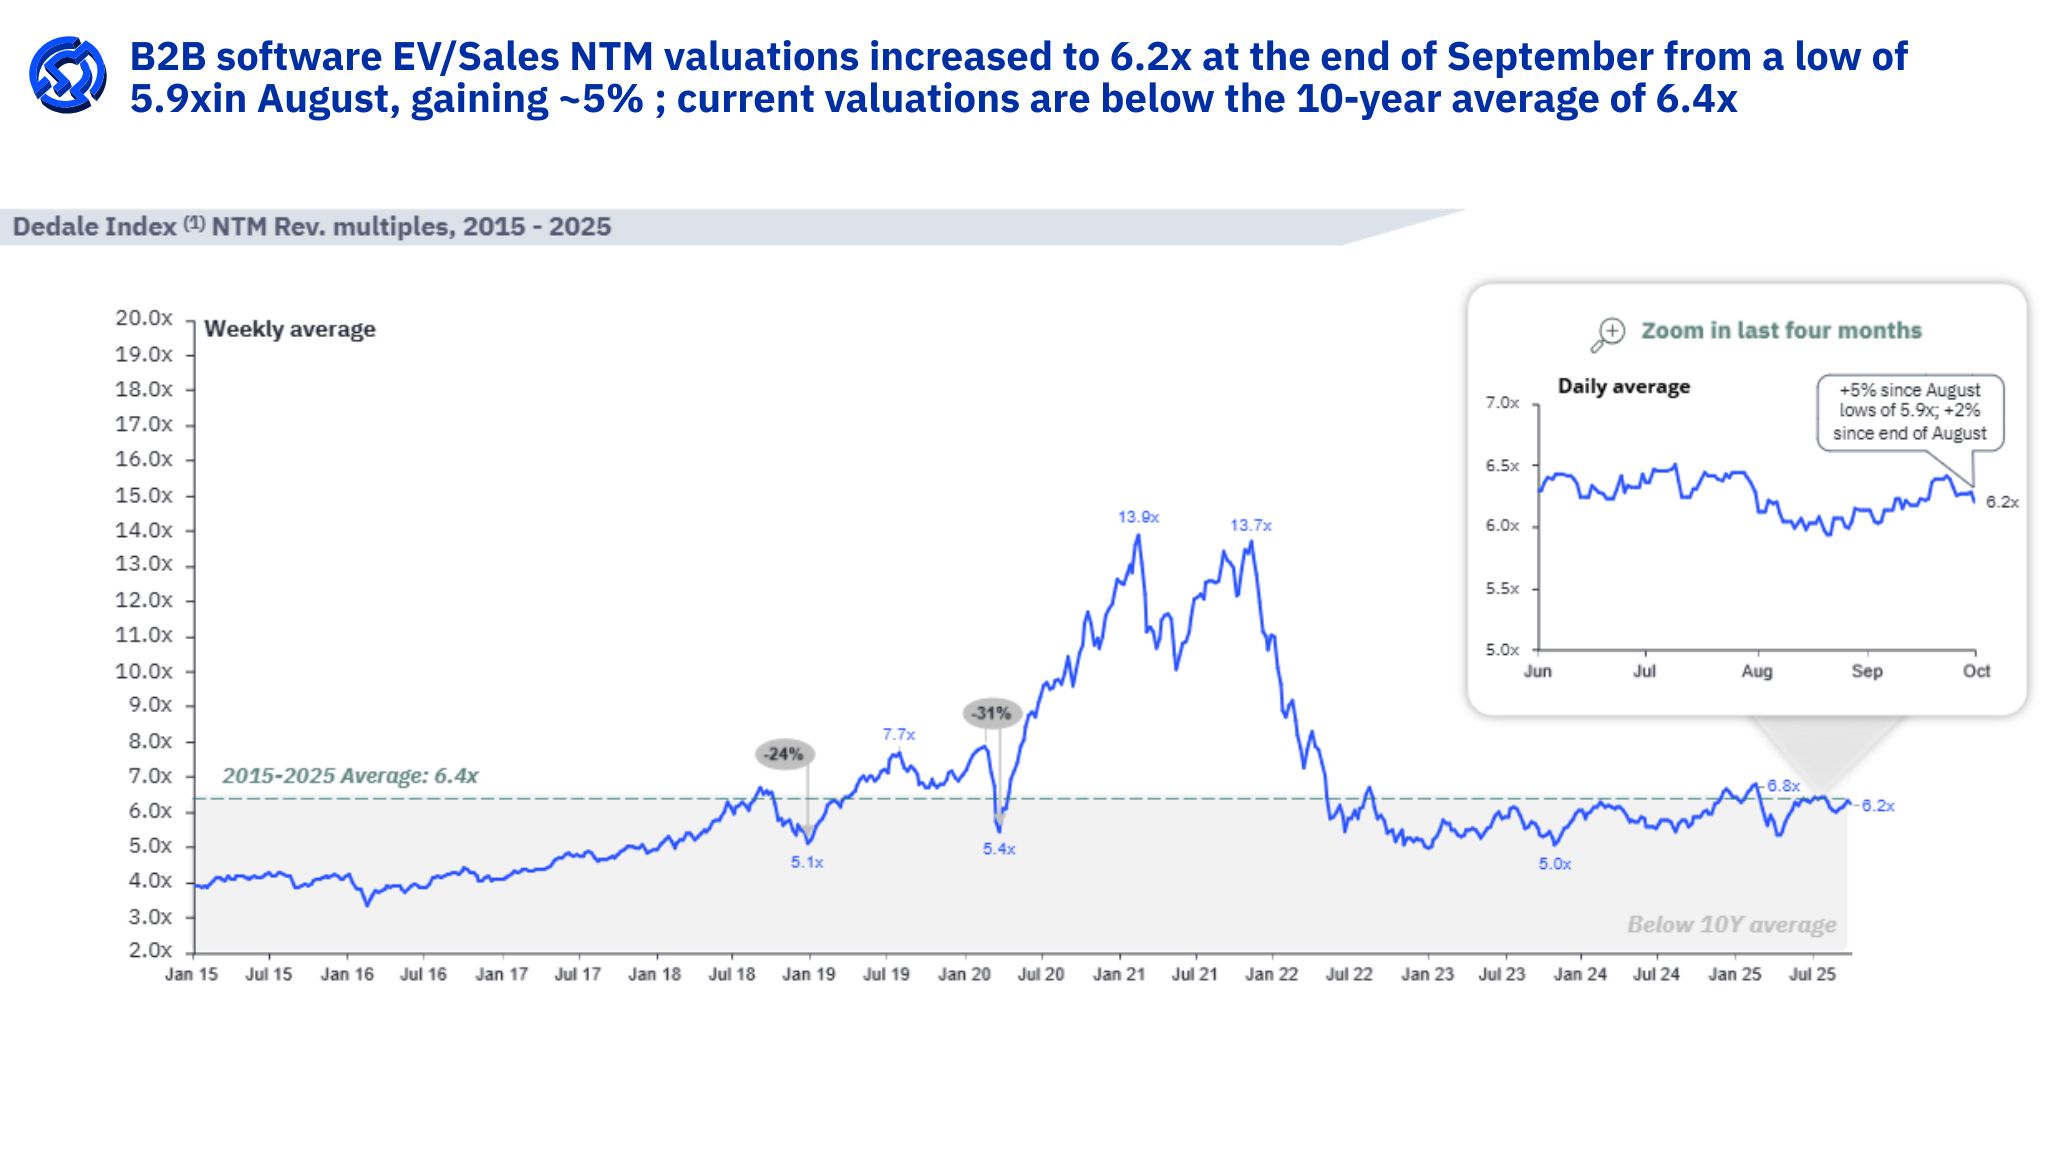
Valuations recovered +5% from August lows, with theB2B software universe now trading at:
- EV/Sales: 6.2x (vs. 10y avg 6.4x)
- EV/EBITDA: 22.8x (vs. 10y avg 27x)
High-growth companies (>20% revenue growth) are now valued at 12.6x EV/Sales, the only cohort posting positive YTD gains(+11%).
Mid-growth firms (10–20% growth) trade at 6.4x, while low-growth peers remain near 4.0x.
Rule of 40 companies trade at 11.1x, whilesub-20 companies hover near 3x.
The North America vs. Europe premium widened further to +90% (7.1x vs. 3.7x), driven by stronger expected growth (11% vs. 3%).
Deal Flow
Private equity and corporate M&A activity accelerated sharply in Q3, confirming 2025 as a rebound year.
Mega-deals (> $1B) are returning, reflecting improved debt markets and renewed buyout appetite.
Notable transactions included:
- Workday’s acquisition of Sana – an AI learning and search platform – for $1B+, implying a >100x revenue multiple. This reflects the defensive race among incumbents to become “AI-powered.”
- Cadence’s $3B acquisition of a Hexagon division in industrial software, valued at 11.5x revenue, underscoring consolidation and strong valuations in the sector.
- Continued activity in GRC, RegTech, LegalTech, and Infrastructure software,with deals involving Keensight, CVC, and Neuberger Berman among others.
On the venture side, AI continues to dominate funding:
- Over $140B invested YTD, with mega-deals (>$500M) now representing ~70%of 2025 deal value.
- Standout rounds: Open AI ($40B), Anthropic ($12B), xAI ($10B), Cognition AI (DevOps), Ramp (CFO software), and Cohere (foundational models).
What to Watch
IPO momentum and public market sentiment
Public listings are gradually reopening, with strong early signs in H2 2025.
Recent IPOs Netskope (Cybersecurity, $500M revenue, +30% growth) and Via Transportation (Mobility software, $300M revenue, +35% growth) illustrate selective investor appetite for high-growth, high-quality assets.
Macro stability and valuation gaps
The Fed’s dovish turn supported valuations in North America, while Europe remains hampered by weak growth expectations. The 90% transatlantic premium is at its highest in five years.
Segment trends and earnings insights
Q2 earnings were broadly positive across the board:
- Oracle: +359% YoY growth in cloud infrastructure backlog (RPO),signaling long-term momentum.
- Salesforce: $1.2B AI-driven ARR (+120% YoY), though growth slows to+10% overall.
- Rubrik: Beat expectations but sold off amid concerns over one-off revenues.
- Guidewire: Strong cloud transition; 75% of ARR now cloud-based.
- Synopsys: Impacted by U.S.–China export restrictions, highlighting policy risk in semiconductors.
AI adaptation, cybersecurity resilience, and cloud transformation remain key earnings themes.
Investment Watchlist
Top names this month:
- ServiceNow – workflow automation leader, Rule of 53, strong free cashflow margins.
- Datadog – observability platform with +20% growth and healthy profitability.
- Dynatrace – application monitoring, attractive entry point post-valuation reset.
- HubSpot – renewed affordability, strong profitability and AI initiatives.
- Snowflake – data management leader, strong FCF and AI investments.
- Veeva Systems – life sciences software leader, stable high-margin growth.
Want access to the full market session?
Dedale Intelligence’s market sessions provide a curated,data-driven lens into what’s really happening in B2B software, from valuations and macro trends to investment signals and segment-level dynamics.
Contact us to learn more about membership and access the full presentation.

Explore our resources
Frequently asked questions
October 2025 Market Trends: Common Questions
Answers to the most common questions about Dedale's September 2025 B2B software market update.
How did B2B software stocks perform in September 2025?
Dedale's index rose 0.7%, trailing the S&P 500 (up 3.2%) and Nasdaq (up 5.0%), with mega-caps like Oracle and Microsoft up nearly 30% year to date.
What happened with interest rates in September 2025?
The Federal Reserve cut rates by 25 basis points, its first cut of the year, as US inflation rose to 2.9%, while the ECB held its deposit rate at 2.0%.
What were the notable deals in September 2025?
Workday's $1 billion-plus acquisition of Sana at a more than 100x revenue multiple, and Cadence's $3 billion acquisition of a Hexagon division at 11.5x revenue.
Newsletter
Fresh insights, straight to your inbox
Trusted by 2,000+ clients
Get started
Investor, operator, or industry expert, there's a path for you.